
All three major indexes are higher before the bell, though Treasury yields remain elevated
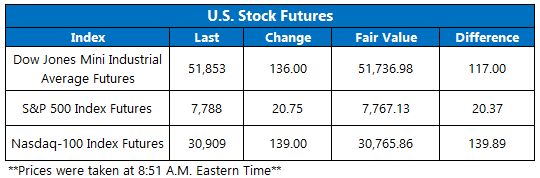
Stock futures are higher this morning as oil prices retreat. Futures on the Dow Jones Industrial Average (DJI) and Nasdaq-100 Index (NDX) are both up over 130 points, while S&P 500 Index (SPX) futures are firmly higher as well. West Texas Intermediate (WTI) crude is down 2%, near $92 per barrel amid optimism surrounding U.S.-Iran negotiations and a potential reopening of the Strait of Hormuz.
Treasury yields remain elevated following yesterday's surge, with the 10-year note hovering above 5.1%. Investors are also digesting Chinese President Xi Jinping's White House visit. Meanwhile, the Dow is headed for a fourth-straight weekly loss, while the S&P 500 and Nasdaq are on track to finish the week higher.
Continue reading for more on today's market, including:
- Back to the basics: How stock splits and buybacks work.
- Aerospace stock could bounce off this key trendline.
- Plus, AKAM soars on Anthropic deal; COST brushes off earnings beat; and SNPS extends rally on upgrade.
5 Things You Need to Know Today
- The Cboe Option Exchange saw roughly 2.1 million call contracts and 1.2 million put contracts traded on Thursday. The single-session equity put/call ratio rose to 0.55, while the 21-day moving average remained at 0.59.
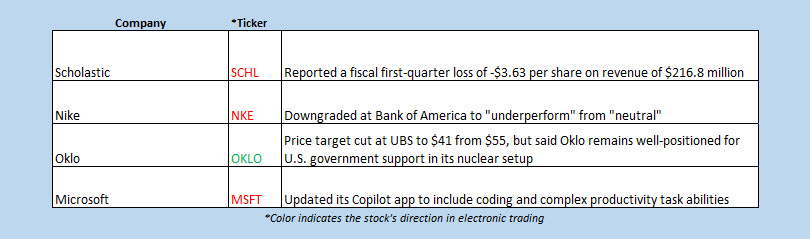
- Akamai Technologies Inc (NASDAQ:AKAM) is up 16% premarket, after the company announced a a seven-year cloud services agreement with Anthropic valued at $11.6 billion. Coming into today AKAM is sporting a 26.5% year-to-date lead.
- Costco Wholesale Corp (NASDAQ:COST) is 0.4% lower before the bell, despite better-than-expected fiscal fourth-quarter earnings, revenue, and comparable sales. Year to date, COST is up 4%.
- Synopsis Inc (NASDAQ:SNPS) is up 3.8% in electronic trading, after an upgrade from HSBC to "buy" from "hold," with a price-target hike to $700 from $490. This comes just one day after BNP upgraded the stock to "neutral" from "underperform." Should these gains hold, SNPS will mark its eighth-straight win, though the shares are still down 9.5% year to date.
- There will be plenty of economic data to kick off October next week.
Investors Unpack Trump-Xi Meeting, Economic Data
Asian markets finished the day a mixed bag, as investors weighed the global bond selloff with a breakout from Japanese-traded Oracle (ORCL) shares, after the company posted record fiscal first-quarter earnings. Japan’s Nikkei jumped 1.3%, while Hong Kong’s Hang Seng lost 1%. South Korean and mainland China stocks were closed for holiday. Elsewhere, in a state media readout of the meeting with President Trump, Chinese President Xi Jinping expressed willingness to cooperate with the U.S. on artificial intelligence.
European sentiment is cautiously higher so far today, as a slew of data rolls in. In Germany, the Nuremberg Institute for Market Decisions (NIM) showed its October Consumer Climate report at -30.6, its lowest level since April and down from September’s -26.8. Meanwhile, lending growth from the European Central Bank (ECB) showed a slowdown to 4.2% from 4.4% month-on-month, while household loans remained stable at 3.1%. At last glance, London’s FTSE 100 is up 0.3%, France’s CAC 40 has added 0.2%, and Germany’s DAX leads with a 0.7% gain.