
A profit-taking mentality would not be all that surprising
Today brings the last trading day of the month. If August is a winner, the S&P 500 Index (SPX—7,711.76) will have to close above 7,489.72, the July close. For a long-term investor, this is welcome news.
For a trader who may have increased their exposure to the broader market on Aug. 4 due to the breakout above two-month range highs and the June high, they have nothing to show for it because Friday’s SPX close at 7,712 was below that Aug. 4 close at 7,736. In other words, we could be in another holding pattern, with a one-day move that pushed the SPX out of its mid-May to early August range showing no significant follow-through.
“Market participants are facing a long list of uncertainties now, the latest being the deficit hitting $40 trillion last week and longer-term interest rates rising with the deficit, plus the potential inflationary impact of a weakening dollar. This is in addition to the U.S.-Iran conflict and resulting higher oil prices, the AI buildout and its impact on utility prices, and the upcoming midterm elections.”
- Monday Morning Outlook, August 24, 2026
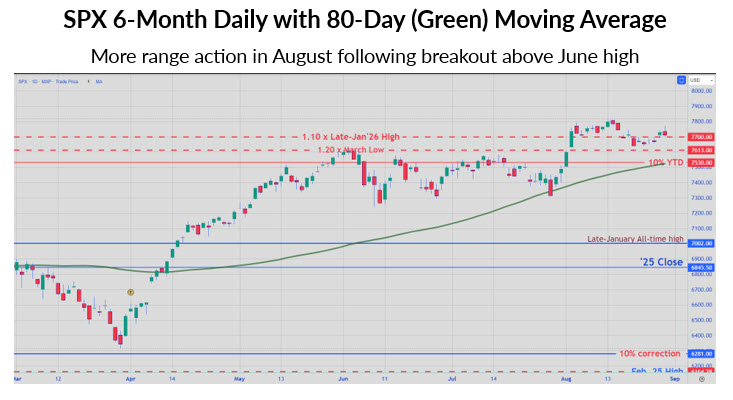
In recent weeks, the SPX was seesawing around the 7,700-century mark, which could be a symptom of a profit-taking mentality. Note in the chart below that the 7,700 level is 10% above the late-January 2026 high. As such, those that bought the mid-April breakout above that high could be locking in some of their gains after the 10% rally. Such price action is similar to the SPX’s behavior around the 7,530 level in mid-May through July. The 7,530 level is 10% above the 2025 close and, as such, a profit-taking mentality may have surfaced among those anchoring to the 2025 close.
With a litany of uncertainties being thrown at traders and investors, a profit-taking mentality would not be all that surprising as human emotions take over and the “anchoring effect” is very much at play. The best way for me to explain the range action is as a potential battle in which overweight fund managers (see last week’s commentary on the Bank of America survey) are not providing follow-through buying power, while short covering (see last week’s commentary) keeps pullbacks in check as the SPX lingers in all-time-high territory.
Tuesday rings in the month of September. Since 2000, it has been an exact coin flip as to whether the SPX finishes the month higher or lower. The past two have been positive, with September 2024 producing a 2% gain and last year generating an impressive 3.5% gain, on the heels of the four prior years producing losses.
For pessimists, September 2022 was during a midterm election year, and the SPX suffered a 9.3% setback. But for optimists, September 2010 was also a midterm election year, and the SPX rallied 8.8% in September. For me, this is a healthy reminder that “Anything can happen” and this is clearly reflected in the stats that I just quoted.
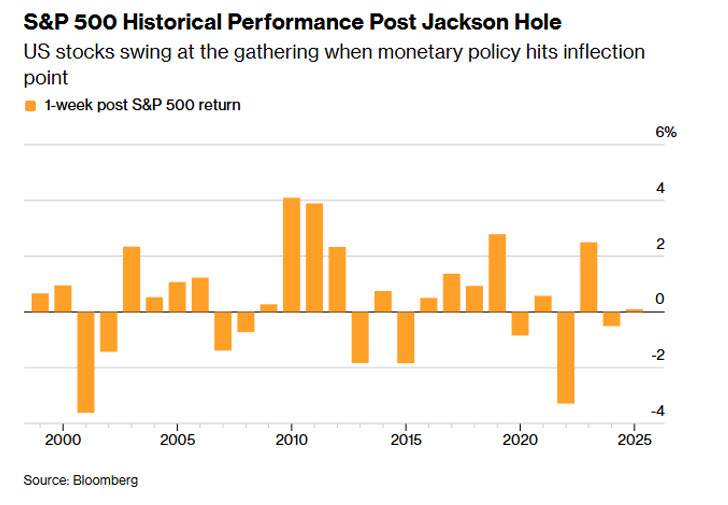
“Despite a few exceptions, a Fed chair’s speech at the symposium normally isn’t a big catalyst for stocks — unless it comes before a crucial shift in monetary policy. Since 2000, the S&P 500 Index has gained just 0.4% on average in the week following the gathering, data compiled by Bloomberg show. And options markets aren’t pricing in any fireworks this time either.”
- Bloomberg, August 28, 2026
As longtime readers know, I like to pass along quotes and charts of interest that I run into the prior week and make comments on them, especially as they relate to how the market could be impacted in the short or longer term.
The graph below is from the article that I excerpted above. The Fed and where interest rates are headed is one of the major uncertainties market participants have been navigating. This has come amid persistent inflation, higher oil prices since the U.S.-Iran conflict began, and new Fed Chair Kevin Warsh -- whose first appearance at the annual Jackson Hole central banker summit was Friday morning.
My thoughts on the historical market reactions were as follows and could be worth considering, especially if you are a swing trader, in the following week:
- The article is correct in that a majority of the time there isn’t a huge move one week after the Jackson Hole meeting.
- Based on the data from the past 25 years, there is a 40% chance of an absolute move of 1.8% or greater one week later. This is slightly greater than the 34% at-any-time probability of a one-week absolute move of 1.8% or more.
- Plus, 16% of the time following Jackson Hole, there was a 3% or more absolute move one week later. This doubles the 7%-8% probability of an absolute move of 3% or greater in any one week going back 25 years.
The takeaway is that the probability of a big move this week is less than a coin toss. However, it should be noted that the chance of a significant absolute move of 3.8% or more is double the normal week – a one-in-six chance.
Todd Salamone is Schaeffer's Senior V.P. of Research.
Continue reading: