
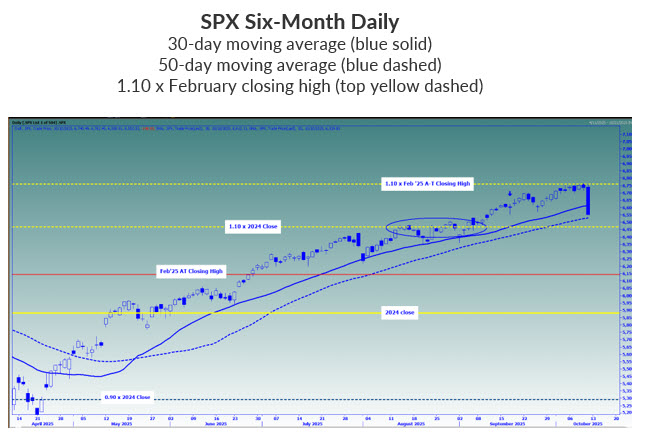
Last week's price action brought forward several anticipated levels for the SPX
“The next potential pause or short-term inflection point to watch for is 6,760, which is roughly 10% above the previous all-time closing high in February…as they anchor to the 10% profits they have realized after buying the breakout…Regardless, whether we get to 6,760 in the coming days, continue to key to the SPX’s 30-day moving average for clues that the momentum could be slowing and/or reversing.”
- Monday Morning Outlook, September 22, 2025
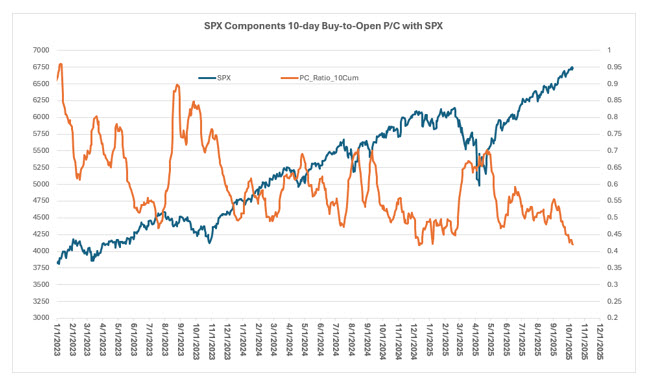
“A short-term hesitation or pivot lower from this (SPX 6,760) level would not be a huge surprise, with option buyers on SPX component stocks buying calls relative to puts at a rate that has historically preceded market weakness."
- Monday Morning Outlook, October 6, 2025
Levels that I have been anticipating for the past few weeks about being potentially important for the S&P 500 Index (SPX -- 6,552.51) were right on cue when observing last week’s price action.
For example, note the pause at or just below the 6,760 level since the beginning of the month and going into Friday’s trading session. With the SPX short-term overbought as it approached 6,760, it wasn’t a surprise to see a hesitation in this area, despite the tremendous momentum higher. As anticipated, my thought is that profit-taking among bulls became more pronounced in this area as those that bought the June breakout above the February 2025 closing high likely lightened up on their exposure, happy with the 10% gain in a three-month period.
“Some very strange things are happening in China! They are becoming very hostile, and sending letters to Countries throughout the World, that they want to impose Export Controls on each and every element of production having to do with Rare Earths…One of the policies that we are calculating at this moment is a massive increase of Tariffs on Chinese products…”
- U.S. President Donald Trump, Truth Social, October 10, 2025
If traders were reducing bullish positions Monday through Thursday and such actions created the lid just below and around the 6,760 level, this profit-taking proved timely. Timely because the SPX sold off sharply Friday morning in response to a post on Truth Social by President Donald Trump, threatening massive tariffs on China and bringing tariff uncertainty back to the forefront.
“…the net short position among large speculators on CBOE Volatility Index (VIX - 16.65) futures is the largest since August 2022, which preceded a 10% decline in the SPX into early October of that year. A caveat to this optimism (a short position on volatility is effectively a bullish view on stocks) is that short positions on VIX futures might be more justified at present, with the SPX at an all-time high. This could be considered a short-term risk factor. In August 2022, the SPX’s technical backdrop was not nearly as strong…”
- Monday Morning Outlook, October 6, 2025
With the SPX selling off on Friday, the Cboe Volatility Index (VIX -- 21.66) surged higher. The pop came as large speculators on VIX futures (typically hedge funds) were positioned for lower volatility – the biggest bet pointing toward lower volatility in over three years from this group.
An unwind of the short volatility trade is a bigger risk with the SPX’s close below its 30-day moving average. If there is a massive closing of short volatility trades following Friday’s decline in the stock market, this would likely be accompanied by more selling in the stock market since stock and volatility direction have an inverse relationship.
That said, there is hope for equity bulls and volatility bears. Note that the VIX has experienced two peaks around the late-May closing high in the 22.30 area. This was the site of Friday’s high too.
Additionally, Friday’s VIX close was barely above 21.35, or 50% above the August closing low.
As such, those anchoring to the August low or previous VIX highs could be volatility sellers, which would at least put a temporary pause on the VIX advance and equity market selloff.
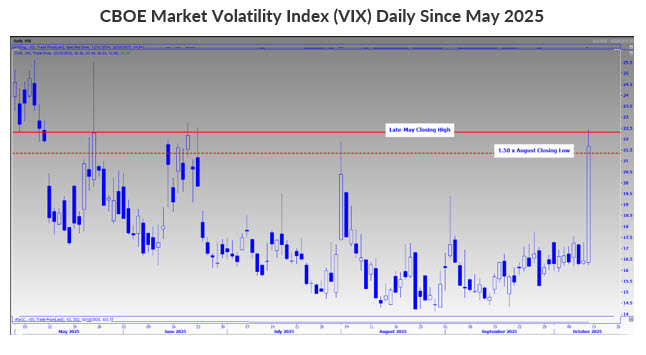
A bold VIX close above 22.30, in my opinion, would be a yellow flag for even higher VIX levels and lower equity prices in the weeks ahead. As I mentioned in previous weeks, slowing momentum -- as measured by the SPX’s close below its 30-day moving average -- heightens (but does not guarantee) correction risk since sentiment indicators are showing optimism among short-term traders.
If short-term traders view Friday’s selloff as a “risk-off” cue in the coming weeks it would create a headwind, as active fund managers reduce exposure from an almost fully invested equity position to stocks. Plus, equity option buyers could view more put buying opportunities relative to call buying opportunities, sending the put/call volume ratio higher from the extreme lows present. A turn higher in the buy (to open) SPX components put/call volume ratio tends to be accompanied by equity market weakness.
Risks of a pullback have increased. Will the cross below the SPX’s 30-day moving average trigger a sell signal as it did in July 2024 and this past February? Or, will this late-October to early-November period be when a cross below the 30-day moving average is met with immediate support at the 50-day moving average, which sits only 22 points below Friday’s close? Or, will it be like last December, when a cross below the SPX’s 30-day moving average led to a volatile chop into the February peak?
Momentum has weakened and this has caught many short-term traders off guard, increasing deeper pullback risk. If you weren’t hedged for correction risk, now is the time to do so, albeit the bears will have to push the SPX below other support levels, such as the 50-day moving average and 6,470, where the SPX paused in August.
Continue Reading: